FinTech Software Development in Gqeberha

A fintech product built in Gqeberha often serves the automotive manufacturing and export trade that the city runs on, since the area is home to vehicle assembly plants, a dense network of component suppliers, and one of the country's busiest ports. As a fintech software development company serving Gqeberha businesses, we design the payment and credit architecture around supplier payment cycles and export settlement timing, since manufacturing and trade finance carry different data requirements than a standard consumer payment build.

Start a fintech build
Rated 5.0 on Clutch Reviews
  • Banking Solutions
  • Payment Solution
  • Insurance Solution
  • Lending Solution

85%

Long-term Partnerships

75%

Mid-to-Senior Engineers

5+

Avg. Years of Engineer Experience

98%

Would Recommend Us

These brands, Trust Us
Bandhan Bank logoPaywize logoDecathlon logoKurlon logoAirAsia logoSofttek logoNandi Toyota logoSABA Hospitality logoDimaak Tours logoMadras Mandi logoQoruz logoToneTag logoCurleyStreet Media logoEverest DX logoZEISS logoAditya Birla Group logoVIA-IOM logoPerkins&Will logoTalkwalker logoCovea logoHelp Cars logoLe Pain Quotidien logoMeltwater logoSangeetha logoOdessa logoBandhan Bank logoPaywize logoDecathlon logoKurlon logoAirAsia logoSofttek logoNandi Toyota logoSABA Hospitality logoDimaak Tours logoMadras Mandi logoQoruz logoToneTag logoCurleyStreet Media logoEverest DX logoZEISS logoAditya Birla Group logoVIA-IOM logoPerkins&Will logoTalkwalker logoCovea logoHelp Cars logoLe Pain Quotidien logoMeltwater logoSangeetha logoOdessa logo

You are probably here because one of these is true.

Where are you right now?

01

You're building a financial product for a manufacturer or exporter.

A payment or lending product built for an automotive supplier or export business in Gqeberha needs to work with purchase orders, delivery schedules, and shipping documents as inputs, not a simple transaction flow. The architecture decisions made early determine how cleanly the product ties payment and credit events to that underlying manufacturing or trade activity.

02

Your client needs supplier payment or trade finance, not a consumer product.

A component supplier in an automotive supply chain often needs to get paid on a schedule tied to delivery, not a standard invoice cycle, since just-in-time manufacturing depends on predictable cash flow at every tier of the supply chain. A credit model that ignores this is one of the common causes of fintech failure, and it changes the payment timing and credit logic more than the underlying payment rails.

03

Your financial software works but will not scale.

Handling payments and credit for a handful of suppliers is one problem; handling it for a full tiered supply chain with dozens of Tier 1, 2, and 3 vendors is a different one entirely. Systems that track this manually or in simple spreadsheets at a small scale usually break down once the number of relationships and export markets grows.

What we build across finance.

FinTech Software Development in Gqeberha: What We Build

Most fintech projects in Gqeberha start with one or two of these service areas. All four are part of the same fintech software development practice.

Banking Solutions

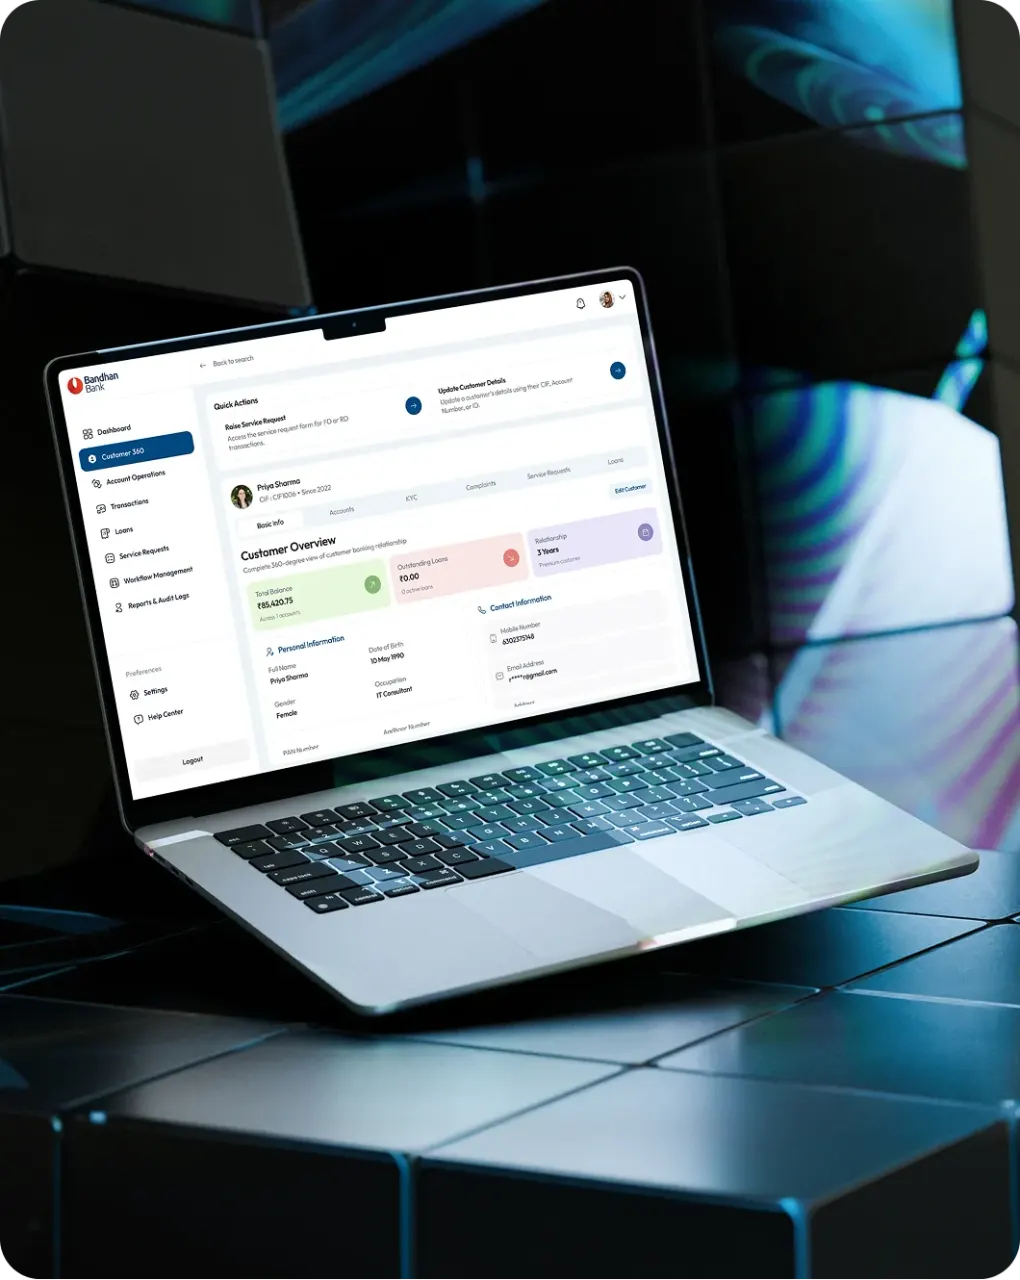
Digital banking platforms, core banking integration, and mobile banking.

Digital banking platformsBusiness banking portalsCore banking integrationMulti-entity account structuresCorporate treasury tools

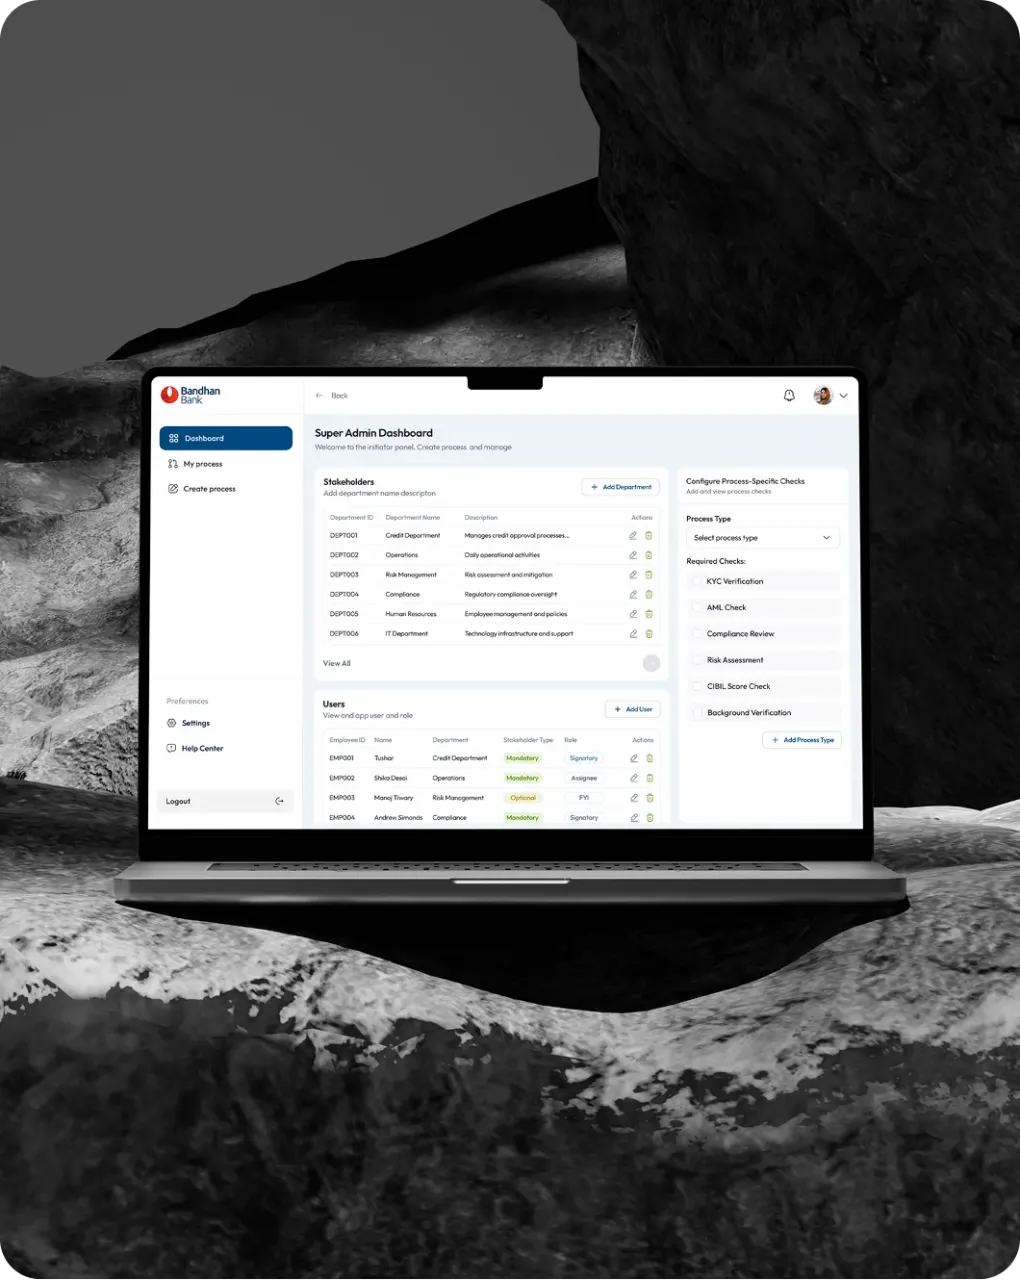
Banking software built for a manufacturing or export client in Gqeberha often needs to support multiple entities and currencies under one corporate structure, not a single domestic retail account. We design the account architecture around that structure from the start.

Payment Solution

Payment aggregation, switching, settlement, and merchant infrastructure.

Supplier payment infrastructureExport and trade payment processingMulti-currency settlementMerchant payment infrastructureReconciliation and settlement

In an automotive supply chain or export business, the moment a payment is due is usually set by a delivery milestone or a shipping document, not a checkout button. We connect the payment trigger to that underlying event directly, so a delivery confirmation or a bill of lading is what actually moves money, not a separate manual approval step.

Insurance Solution

Insurtech platforms, policy management, and claims processing.

Insurtech platformsTrade credit insurancePolicy managementClaims processing automationCargo and export insurance

Insurance products distributed through a manufacturing or export channel in Gqeberha need policy issuance and claims handling that ties to a specific shipment, contract, or trade credit exposure, not a standalone insurance app. We build the policy engine and claims workflow to fit that distribution model.

Lending Solution

Loan origination, credit scoring, and repayment infrastructure.

Alternative credit scoringLoan origination systemsSupplier and purchase order financingRepayment infrastructure

A component supplier's real track record often lives in purchase order history and on-time delivery rates, not in a credit bureau file. Our scoring models read from that record directly, so a supplier with a strong delivery history but a thin formal credit file isn't turned away by a system that only knows how to look at one kind of data.

Part of

FinTech & Banking, our practice for regulated software that ships secure, compliant, and on time.

See all FinTech services

How a build runs from first session to go-live.

How fintech software development runs in Gqeberha

Every fintech software development project in Gqeberha follows the same phase structure, adjusted for whether the client is a manufacturer, an exporter, or a standard fintech client. Senior engineers from the first session.

Start a fintech build

{ 01 }· Week 1

Map the supply chain or trade workflow and the payment triggers

We identify which manufacturing, delivery, or export events need to trigger a payment, credit decision, or insurance claim before any design begins.

Trade eventsPayment triggersCredit decisions

{ 02 }· Weeks 2 to 3

Design the integration and credit architecture

We design the data model, the integration contracts, and the credit or underwriting logic alongside the product architecture, the same way we approach every market in our fintech Africa practice, so the build reflects how the client's supply chain or export process actually works.

ComplianceIntegrationsArchitecture

{ 03 }· Build

Two-week sprints with working integrations

Each sprint delivers a working payment or credit feature, tested against real purchase order and delivery data, not a simplified test dataset.

SprintsIntegrationsTesting

{ 04 }· After launch

Stay compliant as requirements evolve

We stay on the product through the first regulatory review cycle and handle regulatory updates, integration changes, and reporting changes as they arise.

MonitoringRegulatory updatesReporting

Why fintechs pick us for this.

Why teams choose Zethic for fintech software development in Gqeberha

We design around manufacturing and trade data, not just payment data

A payment or lending product built for a supplier or exporter needs to understand purchase orders, delivery schedules, and shipping documentation as inputs, not just a transaction amount. We treat that manufacturing and trade data as a core part of the architecture, not something added on to a standard payment build.

Supplier finance has its own credit logic

Getting a component supplier paid on a delivery-linked schedule is a different underwriting problem than consumer lending, and getting that logic wrong shows up as cash flow strain across the supply chain, not a simple missed payment. We design the credit model around delivery performance data instead of a generic repayment schedule.

We build the credit scoring layer around the data the client actually has

Automotive suppliers and exporters often have delivery and purchase order records instead of a conventional credit history, so the scoring model needs to work from that data. Our AI credit decisioning work is built around exactly that kind of alternative data signal.

The same engineer designs it and builds it

Whoever works out how the payment triggers and the credit logic fit together for a supply chain is also the person writing that code, so nothing gets lost between a design conversation and an actual sprint.

Questions, answered.

FAQs: FinTech Software Development in Gqeberha

Yes, automotive component suppliers and manufacturers are common clients in Gqeberha given the area's role as an automotive manufacturing hub, and their payment and credit needs differ from standard consumer fintech products. We design those products around purchase order, delivery, and production data, not a generic transaction model.

Trade finance is usually tied to a specific shipment, contract, or purchase order, with the financing structured around when goods move and when payment is due, not a general-purpose loan against the business as a whole. We design origination and monitoring systems around that transaction-specific structure.

Yes, and for a supplier finance product this integration is usually central, since payment and credit decisions are triggered by purchase order and delivery data in those systems. Our procurement and demand forecast experience means we understand both sides of that integration, not just the payment side.

Export and trade credit insurance need to account for buyer risk in the destination market, not just the exporter's own creditworthiness, which is a different underwriting question than standard business insurance. We design the policy and claims workflow to capture that buyer-side risk as part of the underlying data model.

Timelines depend on how much integration with existing procurement, manufacturing, or export systems the product needs, since that scope is usually larger than a standalone consumer fintech build. A product with a clearly defined integration scope typically moves faster than one where that mapping is still happening during the build. The same phase structure runs across our wider fintech software development in Africa practice.

Building a fintech for the Gqeberha market?

Tell us what you're building and who it needs to serve. A senior engineer replies within one working day with a clear starting point.

Zethic Clutch reviews
Zethic - The Manifest Most Reviewed Design Company in BengaluruZethic - GoodFirms Top Development CompanyZethic - The Manifest Most Reviewed App Development Company in BengaluruZethic - Clutch Top-Rated UI/UX Design Studio in IndiaZethic - Rankwatch Top Web Development AgenciesZethic - The Manifest Most Reviewed Web Developers in BengaluruZethic - Top Developers Top Mobile App Developers in Bengaluru

Tell us the build

What you're building and which obligations apply to it. We sign an NDA so it stays private.

We map compliance first

A senior engineer maps licensing, payment integration, and reporting before any architecture gets drawn.

It ships production-ready

The engineers who scope the integration write the code against it, so nothing gets lost in a handoff.

Building a fintech? Start a fintech build