FinTech Software Development in Port Louis

A fintech product built in Port Louis often has to answer to two regulators at once: the Bank of Mauritius for anything touching domestic payments and banking, and the Financial Services Commission for products aimed at international clients. As a fintech software development company serving Port Louis businesses, we design the licensing path, the compliance schema, and the data architecture around whichever regulator actually applies, so the product isn't built against the wrong rulebook.

Start a fintech build
Rated 5.0 on Clutch Reviews
  • Banking Solutions
  • Payment Solution
  • Insurance Solution
  • Lending Solution

85%

Long-term Partnerships

75%

Mid-to-Senior Engineers

5+

Avg. Years of Engineer Experience

98%

Would Recommend Us

These brands, Trust Us
Bandhan Bank logoPaywize logoDecathlon logoKurlon logoAirAsia logoSofttek logoNandi Toyota logoSABA Hospitality logoDimaak Tours logoMadras Mandi logoQoruz logoToneTag logoCurleyStreet Media logoEverest DX logoZEISS logoAditya Birla Group logoVIA-IOM logoPerkins&Will logoTalkwalker logoCovea logoHelp Cars logoLe Pain Quotidien logoMeltwater logoSangeetha logoOdessa logoBandhan Bank logoPaywize logoDecathlon logoKurlon logoAirAsia logoSofttek logoNandi Toyota logoSABA Hospitality logoDimaak Tours logoMadras Mandi logoQoruz logoToneTag logoCurleyStreet Media logoEverest DX logoZEISS logoAditya Birla Group logoVIA-IOM logoPerkins&Will logoTalkwalker logoCovea logoHelp Cars logoLe Pain Quotidien logoMeltwater logoSangeetha logoOdessa logo

You are probably here because one of these is true.

Where are you right now?

01

You're not sure which Mauritius regulator applies to your product.

Whether a fintech product falls under the Bank of Mauritius or the Financial Services Commission depends on whether it serves the domestic market or clients based outside Mauritius, and getting that wrong early means redesigning the compliance model later. We help map the product to the right regulator and licence category before any architecture decision gets made.

02

Your product works elsewhere but needs a Mauritius entity.

International fintech companies often set up in Mauritius for the offshore financial services structure, which means the product needs to be built for FSC oversight even if the underlying team and users sit outside the country, the same way we approach every market in our fintech Africa practice. This changes the compliance and data residency model more than it changes the product itself.

03

Your financial software works but will not scale.

A fintech product that handles a modest transaction volume behaves differently once it needs to settle through Mauritius's national payment switch at real scale, and scaling failures at this stage are a common reason fintech builds stall. The reconciliation and reporting logic that worked early often needs restructuring to hold up under that load.

What we build across finance.

FinTech Software Development in Port Louis: What We Build

Most fintech projects in Port Louis start with one or two of these service areas. All four are part of the same fintech software development practice.

Banking Solutions

Digital banking platforms, core banking integration, and mobile banking.

Digital banking platformsMobile bankingCore banking integrationDigital bank licensing supportFinancial inclusion products

Mauritius has opened a licensing path specifically for digital banks, distinct from traditional bank licensing, which changes what a banking build needs to plan for from day one. We design for that licensing path directly, rather than adapting a product built for a market with only conventional banking rules.

Payment Solution

Payment aggregation, switching, settlement, and merchant infrastructure.

MauCAS integrationCard payment infrastructureCross-border payment processingMerchant payment infrastructureSettlement and reconciliation

A payment platform aimed at the domestic Mauritius market needs to settle through the national payment switch, while a platform aimed at international clients is usually built around card acquiring and cross-border processing instead. These are genuinely different builds, and we scope which one applies before writing the integration layer.

Insurance Solution

Insurtech platforms, policy management, and claims processing.

Insurtech platformsPolicy managementClaims processing automationDigital distributionCross-border insurance products

Insurance products originating from Mauritius increasingly serve clients across the wider region, not just the domestic market, which raises different questions about where a claim gets processed and which rules govern it. We build the policy and claims infrastructure to handle that regional reach cleanly from the data model up.

Lending Solution

Loan origination, credit scoring, and repayment infrastructure.

Digital lending platformsAlternative credit scoringLoan origination systemsRepayment infrastructure

Lending products in Mauritius range from consumer digital lending to structured products aimed at businesses operating through the island's international finance sector, and the credit model looks different depending on which one a product is. We build origination and scoring systems matched to the actual borrower base a product is targeting.

Part of

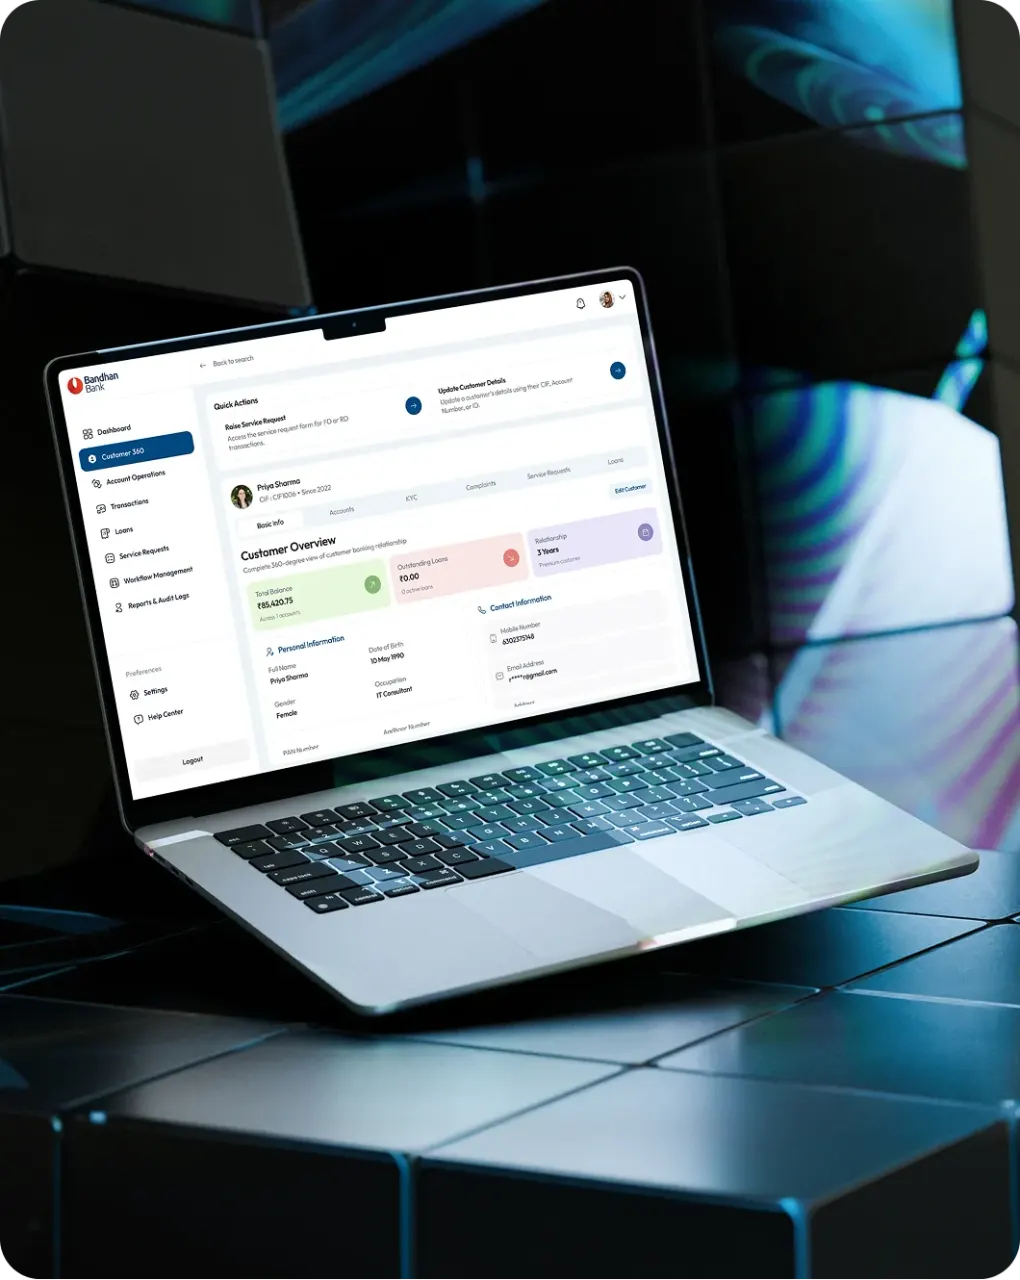
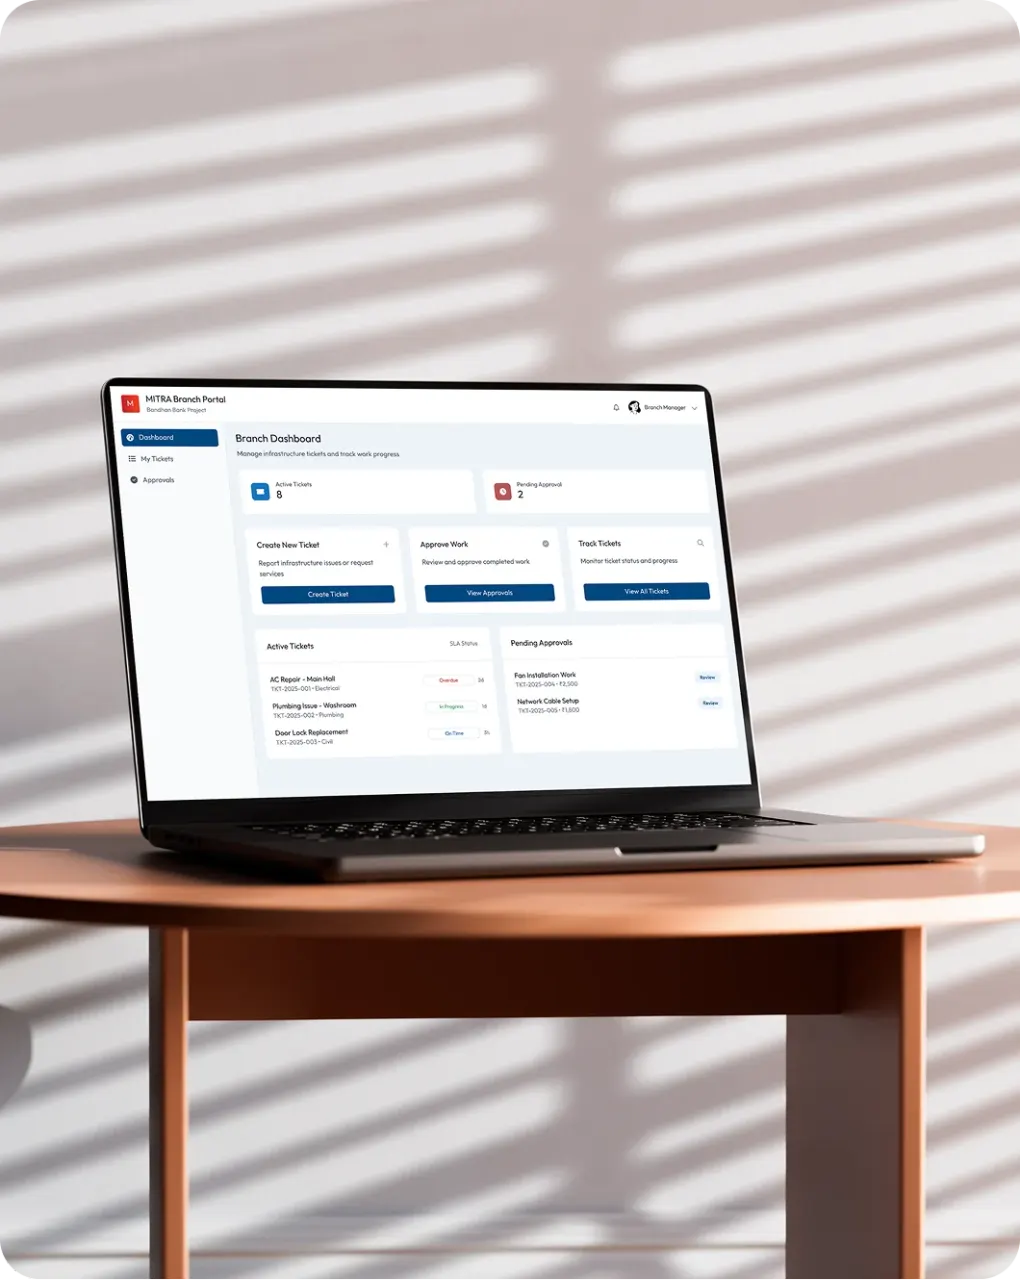
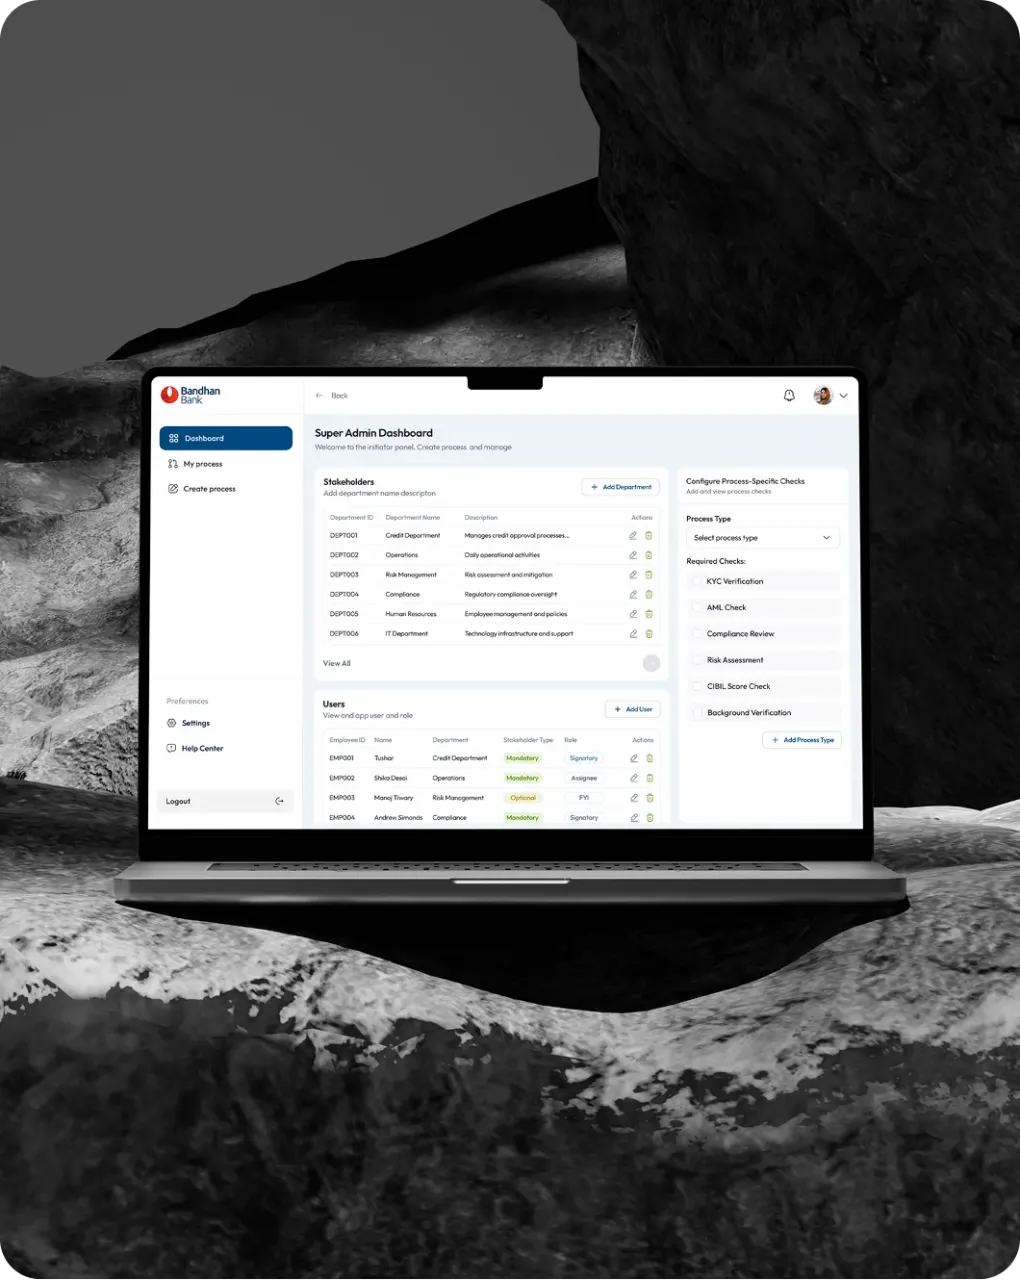
FinTech & Banking, our practice for regulated software that ships secure, compliant, and on time.

See all FinTech services

How a build runs from first session to go-live.

How fintech software development runs in Port Louis

Every fintech software development project in Port Louis follows the same phase structure, adjusted for which regulator applies and the licensing category involved. Senior engineers from the first session.

Start a fintech build

{ 01 }· Week 1

Map the regulator and the licensing path

We identify whether the Bank of Mauritius or the Financial Services Commission applies, and the specific licence category the product needs, before any design begins.

Regulator scopeLicence categoryCompliance schema

{ 02 }· Weeks 2 to 3

Design the compliance and data architecture

We design the KYC schema, the data residency model, and the payment integration contracts alongside the product architecture, drawing on the same banking software development practice we bring to every regulated build, so compliance is structural rather than added later.

ComplianceIntegrationsArchitecture

{ 03 }· Build

Two-week sprints with working integrations

Each sprint delivers a working payment integration or compliance feature, tested against the relevant payment and regulatory environment.

SprintsIntegrationsTesting

{ 04 }· After launch

Stay compliant as requirements evolve

We stay on the product through the first regulatory review cycle and handle regulatory updates, payment switch changes, and reporting changes as they arise.

MonitoringRegulatory updatesReporting

Why fintechs pick us for this.

Why teams choose Zethic for fintech software development in Port Louis

We scope the regulator before we scope the build

A lot of early missteps in Mauritius come from assuming one regulatory path applies when the product's actual client base points to the other. We settle that question first, so the architecture that follows is built against the right rulebook the first time.

Domestic and international builds are not interchangeable

A product built for domestic Mauritius customers and a product built for the island's international financial services sector solve different problems, even when the underlying technology looks similar. We keep that distinction in the architecture rather than forcing one template to cover both.

Cross-border data handling is a design decision, not an afterthought

Products that serve clients outside Mauritius need data residency and privacy rules worked out at the schema level, since getting this wrong is a common reason fintech builds stall after launch. We design for that from the first data model, not after a client asks where their data actually sits.

One team from architecture to production

The engineer who works out the licensing path and the compliance model is also the one writing the code against them. That is the standard we bring to every project we take on.

Questions, answered.

FAQs: FinTech Software Development in Port Louis

It depends on who the product serves: the Bank of Mauritius generally applies to products handling domestic payments and banking, while the Financial Services Commission covers products serving clients based outside Mauritius. Some products end up needing both, depending on the mix of domestic and offshore activity.

A domestic payment product needs to settle through the national switch that Mauritius operates, which shapes the routing and reconciliation logic from the start. We build the integration layer to handle that settlement path alongside any card or cross-border rails the product also needs.

Mauritius has introduced a dedicated licensing path for digital banks that is separate from conventional bank licensing, with its own requirements and a phased approach to reaching full operation. We help map a product's plans against that path early, so the architecture matches the licensing stage the business is actually in.

A product serving clients outside Mauritius needs to work out where data is stored and processed, and which rules govern moving it across borders, as part of the initial architecture. We design the data model and consent handling around that from the start, rather than retrofitting it once a client or regulator raises the question.

Timelines depend heavily on which regulator applies and whether new licensing is required. A product with an existing licence pathway and a defined payment scope typically moves faster than one that needs a new licence application reviewed before it can launch. Timelines are comparable for fintech software development in Johannesburg, though enterprise bank integration usually adds its own testing cycle.

Building a fintech for the Port Louis market?

Tell us what you're building and who it needs to serve. A senior engineer replies within one working day with a clear starting point.

Zethic Clutch reviews
Zethic - The Manifest Most Reviewed Design Company in BengaluruZethic - GoodFirms Top Development CompanyZethic - The Manifest Most Reviewed App Development Company in BengaluruZethic - Clutch Top-Rated UI/UX Design Studio in IndiaZethic - Rankwatch Top Web Development AgenciesZethic - The Manifest Most Reviewed Web Developers in BengaluruZethic - Top Developers Top Mobile App Developers in Bengaluru

Tell us the build

What you're building and which obligations apply to it. We sign an NDA so it stays private.

We map compliance first

A senior engineer maps licensing, payment integration, and reporting before any architecture gets drawn.

It ships production-ready

The engineers who scope the integration write the code against it, so nothing gets lost in a handoff.

Building a fintech? Start a fintech build